Close Menu
TechCentralTechCentral

    Subscribe to the newsletter

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Facebook X (Twitter) YouTube LinkedIn
    WhatsApp Facebook X (Twitter) LinkedIn YouTube
    TechCentralTechCentral
    • News
      Shoprite ranks cybersecurity as its number one risk - Pieter Engelbrecht

      Shoprite ranks cybersecurity as its number one risk

      9 October 2026
      Standard Bank to take up to $200-million stake in OPay - Sim Tshabalala

      Standard Bank to take up to $200-million stake in OPay

      9 October 2026
      Shoprite takes on the banking apps with airtime on Sixty60

      Shoprite takes on the banking apps with airtime on Sixty60

      9 October 2026
      How to tell telemarketers to get lost - officially

      How to tell telemarketers to get lost – officially

      9 October 2026
      Data centres are the new front line in the Russia-Ukraine war

      Data centres are the new front line in the Russia-Ukraine war

      9 October 2026
    • World
      SpaceX takes aim at US wireless carriers with spectrum acquisition

      Starlink is coming for your mobile operator

      9 October 2026
      The AI PC is finally here. It's just very expensive - Jensen Huang, Satya Nadella

      The AI PC is finally here. It’s just very expensive

      8 October 2026
      The memory crunch is making Samsung fabulously rich

      The memory crunch is making Samsung fabulously rich

      8 October 2026
      SpaceX to borrow $40-billion to buy Nvidia chips

      SpaceX to borrow $40-billion to buy Nvidia chips

      7 October 2026
      South Pole neutrino hunter wins Nobel Prize in Physics - Francis Halzen

      South Pole neutrino hunter wins Nobel Prize in Physics

      7 October 2026
    • In-depth

      10 days that changed the course of AI

      21 September 2026
      Meta to the AI industry: slow down without us - Mark Zuckerberg

      Meta to the AI industry: slow down without us

      16 September 2026
      Google DeepMind CEO Demis Hassabis. Image: John Sears

      The plan to stop AI from breaking the world

      16 July 2026
      The internet has a Strait of Hormuz problem

      The internet has a Strait of Hormuz problem

      15 July 2026
      AI boom sparks rally, frenzy and fear

      AI boom sparks rally, frenzy and fear

      11 June 2026
    • TCS
      W&W | LDV's Gerhard Moolman on electric bakkies, fleet orders and 'school fees'

      W&W | LDV’s Gerhard Moolman on electric bakkies and fleets

      9 October 2026
      TCS | Frogfoot sees bigger fibre deals coming - TechCentral Show guests Abraham van der Merwe and Shane Chorley

      TCS | Frogfoot sees bigger fibre deals coming

      8 October 2026
      Meet the CIO | Vodacom's Mohamed Sami on the agentic future

      Meet the CIO | Vodacom’s Mohamed Sami on the agentic future

      5 October 2026
      Lexi Novitske, general partner at Norrsken22, on the TechCentral Show

      TCS | Norrsken22’s Lexi Novitske on how China is winning African tech

      1 October 2026
      TCS | Dominic White and Adam Ely on AI agents going rogue

      TCS | Dominic White and Adam Ely on AI agents going rogue

      29 September 2026
    • Opinion
      When a machine can choose, who does it become? Fanie van Rooyen

      When a machine can choose, who does it become?

      9 October 2026
      Let South Africans jailbreak their way to digital sovereignty - Dirk de Vos

      Let South Africans jailbreak their way to digital sovereignty

      5 October 2026
      South Africa's next energy crisis is in the accounts department - Craig Holmes

      South Africa’s next energy crisis is in the accounts department

      29 September 2026
      The steam engine lesson AI doomsayers keep missing - Sam Clarke

      The steam engine lesson AI doomsayers keep missing

      28 September 2026
      Let South Africans jailbreak their way to digital sovereignty - Dirk de Vos

      Regulating AI: apply the laws we have first

      21 September 2026
    • Company News
      • 1Stream
      • Africa Data Centres
      • AfriGIS
      • Altron Digital Business
      • Altron Document Solutions
      • Altron Group
      • Arctic Wolf
      • Ascent Technology
      • AvertITD
      • BBD
      • Braintree
      • CallMiner
      • CambriLearn
      • CM.com
      • Contactable
      • CYBER1 Solutions
      • Digicloud Africa
      • Digimune
      • Domains.co.za
      • ESET
      • Euphoria Telecom
      • HOSTAFRICA
      • Incredible Business
      • iONLINE
      • IQbusiness
      • Iris Network Systems
      • Kaspersky
      • LSD Open
      • Mitel
      • NEC XON
      • Netstar
      • Network Platforms
      • Next DLP
      • Ovations
      • Paracon
      • Paratus
      • Publishared
      • Q-KON
      • SevenC
      • SkyWire
      • Solid8 Technologies
      • Telit Cinterion
      • Telviva
      • Tenable
      • Vertiv
      • Videri Digital
      • Vodacom Business
      • Vox
      • Wipro
      • Workday
      • XLink
    • Sections
      • AI and machine learning
      • Banking
      • Broadcasting and Media
      • Cloud services
      • Contact centres and CX
      • Cryptocurrencies
      • Education and skills
      • Electronics and hardware
      • Energy and sustainability
      • Enterprise software
      • Financial services
      • HealthTech
      • Information security
      • Internet and connectivity
      • Internet of Things
      • Investment
      • IT services
      • Lifestyle
      • Policy and regulation
      • Public sector
      • Retail and e-commerce
      • Satellite communications
      • Science
      • SMEs and start-ups
      • Social media
      • Talent and leadership
      • Telecoms
      • Watts & Wheels
    • Events
    • Advertise
    TechCentralTechCentral
    Home » Opinion » Genna Robb » Why mobile money has flopped in SA

    Why mobile money has flopped in SA

    By Genna Robb17 July 2015
    Twitter LinkedIn Facebook WhatsApp Email Telegram Copy Link
    Get breaking news on WhatsApp

    genna-robb-180Anyone who has recently spent time in Kenya, Zimbabwe or Tanzania will have noticed the pervasive influence of mobile money on everyday life. People use it for a wide range of purposes from buying airtime to paying taxi drivers to making loan repayments.

    Mobile money has revolutionised financial services in several African countries, lowering transaction costs, driving financial inclusion and providing consumers and small businesses with easy, cheap and safe ways to transact.

    More than that, the experience in Kenya has shown that mobile money can be instrumental in bringing people into the formal economy, generating information on individuals’ transacting behaviour and thus creating better risk profiles — and a credit record — which can be used to offer them financial services that would otherwise be inaccessible.

    The impact on financial inclusion is well documented, but it is not only the poor and unbanked in Kenya who use mobile payments. According to the GSMA, in 2014, 67% of transactions in Kenya’s National Payment System by volume were conducted using mobile money. Small businesses also use mobile payments as a way to pay their workers.

    In Tanzania, mobile money was slower to take off, but is now growing fast. Competition is already providing benefits to consumers in terms of low prices and convenience. In 2014, the major mobile money providers in Tanzania reached an agreement to allow their platforms to interoperate so that customers can send money to recipients with mobile wallets on other networks. This development, unprecedented internationally, allows consumers to benefit from a much bigger payment network.

    So, with such game-changing developments happening on our doorstep, the question for South Africa is: why are we so far behind? A number of attempts to launch mobile payments solutions have failed (including Vodacom’s M-Pesa), although recently both Vodacom and MTN have re-launched their services.

    It is often pointed out that South Africa has a much more sophisticated financial system than other African markets and more people already have access to financial services. In addition, cheap means of transferring money already exist, such as Shoprite’s R9,99 service that allows customers to send money to any Shoprite branch in the country.

    However, in 2014, according to the FinScope survey, 25% of adults in South Africa remained unbanked and of the 23% of adults who sent or received remittance transfers from friends or family within South Africa, the largest proportion, 32%, stated that they sent the cash with a relative or friend.

    Another area that is often cited as holding back developments in South Africa is its rigid regulatory framework. Mobile money proponents cite the flexible approach of the Central Bank of Kenya as a key success factor for M-Pesa. There is no denying that the South African regime is harder to navigate for new entrants.
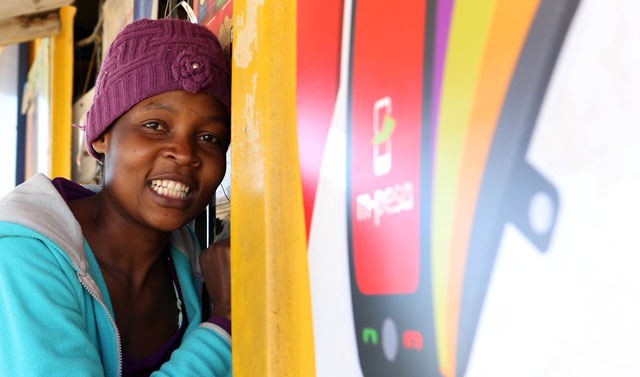
    M-Pesa has failed to live up to Vodacom's expectations in South Africa
    M-Pesa has failed to live up to Vodacom’s expectations in South Africa

    First of all, in the absence of a special dispensation for non-banks or e-money providers (which is the approach taken by the Tanzanian authorities, for example), payments providers in South Africa are treated as banks and subject to the full regulatory compliance requirements (and costs) associated with this.

    This forces providers to partner with banks, necessitating complicated joint ventures where banks naturally would like to see the mobile money product do well, but not too well.

    This approach is unnecessarily stringent and stifles innovation and disruption which would benefit consumers, especially the poor. In fact, mobile payments introduce very little risk into the payment system as the funds sent by customers are typically held in a trust account and not invested or on-lent by the mobile operators as would be done by a bank.

    This is why, in most jurisdictions, mobile money providers have not been regulated as fully fledged banks, but regulators with an eye on financial inclusion have come up with a more proportionate regulatory response. Unfortunately, this does not appear to be high on the regulatory agenda in South Africa.

    Fica regulations are another hurdle in South Africa, although here at least a more proportionate response to risk has prevailed. Exemption 17 allows clients to be registered for mobile money without proof of address or face-to-face ID verification as long as there is a low daily transaction limit.

    The benefits that mobile money can bring through driving competition in the payments space are clear. In Tanzania, to send the equivalent of R500 from one M-Pesa account to another costs only R3,23. Also, mobile money delivers more than just cheap money transfers: the money can remain in the wallet and be used for other transactions such as purchasing electricity. On the back of mobile money platforms, providers can build other solutions and services such as credit and savings products.

    If we truly want to create a more inclusive economy then creating the regulatory space, as other countries have done, for mobile money providers to innovate and compete is an important step.

    • Genna Robb is a senior research fellow at the Centre for Competition, Regulation and Economic Development (CCRED) and an economist at DNA Economics
    • CCRED will be hosting a public platform on mobile money on 22 July 2015. More details are available on the CCRED website
    Add TechCentral as a preferred source on GoogleFollow TechCentral on Google NewsGet breaking news on WhatsApp


    CCRED Genna Robb M-Pesa MTN Vodacom
    WhatsApp YouTube
    Share. Facebook Twitter LinkedIn WhatsApp Telegram Email Copy Link
    Previous ArticleMTN embraces open access for fibre
    Next Article Icasa down to just three councillors

    Related Posts

    Shoprite takes on the banking apps with airtime on Sixty60

    Shoprite takes on the banking apps with airtime on Sixty60

    9 October 2026
    DNI's R500-million bet on Mission Mobile is mostly debt - Timothy Strike

    Behind DNI’s R500-million bet on Mission Mobile

    5 October 2026
    Meet the CIO | Vodacom's Mohamed Sami on the agentic future

    Meet the CIO | Vodacom’s Mohamed Sami on the agentic future

    5 October 2026
    Company News
    Why fintechs need an insurance partner they can trust - Hollard Insurance

    Why fintechs need an insurance partner they can trust

    8 October 2026
    Reusable KYC means the end of 'please upload your ID' - Contactable

    Reusable KYC means the end of ‘please upload your ID’

    8 October 2026
    Eliminating the 'toggle tax': how CRM integration changes customer experience - Martie de Beer

    Eliminating the ‘toggle tax’: how CRM integration changes customer experience

    8 October 2026
    Opinion
    When a machine can choose, who does it become? Fanie van Rooyen

    When a machine can choose, who does it become?

    9 October 2026
    Let South Africans jailbreak their way to digital sovereignty - Dirk de Vos

    Let South Africans jailbreak their way to digital sovereignty

    5 October 2026
    South Africa's next energy crisis is in the accounts department - Craig Holmes

    South Africa’s next energy crisis is in the accounts department

    29 September 2026

    Subscribe to Updates

    Get the best South African technology news and analysis delivered to your e-mail inbox every morning.

    Latest Posts
    Shoprite ranks cybersecurity as its number one risk - Pieter Engelbrecht

    Shoprite ranks cybersecurity as its number one risk

    9 October 2026
    Standard Bank to take up to $200-million stake in OPay - Sim Tshabalala

    Standard Bank to take up to $200-million stake in OPay

    9 October 2026
    Shoprite takes on the banking apps with airtime on Sixty60

    Shoprite takes on the banking apps with airtime on Sixty60

    9 October 2026
    How to tell telemarketers to get lost - officially

    How to tell telemarketers to get lost – officially

    9 October 2026
    © 2009 - 2026 NewsCentral Media
    Built and maintained by Chronon
    • Cookie policy (ZA)
    • TechCentral – privacy and Popia

    Type above and press Enter to search. Press Esc to cancel.

    Manage consent

    TechCentral uses cookies to enhance its offerings. Consenting to these technologies allows us to serve you better. Not consenting or withdrawing consent may adversely affect certain features and functions of the website.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
    🇿🇦 Sign up to the TechCentral newsletter